Beginning January 1, 2027, nearly all homeowners insured under Citizens Property Insurance with wind coverage will also be required to have flood insurance in order to renew their policies. This mandate applies regardless of whether their home is located in a zone designated as high-risk by FEMA or not.
This requirement is part of the final phase of a state law passed in December 2022, which has been gradually implemented over four years.
Previously, only properties situated in high-risk zones or with reconstruction values exceeding $400,000 were subject to this requirement. However, starting in January, the mandate will extend to all residential policies with wind coverage, irrespective of the home's value.
Exempt from this requirement are policies for condominium units, renters' content policies, and those that exclude wind or hail coverage, as confirmed by Hillsborough County.
For thousands of Cuban-American families residing in Hialeah, Miami-Dade, Broward, and Tampa who maintain their policies with Citizens due to favorable pricing, this change represents an additional expense that needs to be budgeted for before their next renewal date.
Citizens does not sell flood insurance directly. Homeowners must procure a policy independently, either through the federal National Flood Insurance Program (NFIP) or a private insurer. The coverage must match or exceed the reconstruction value declared in the Citizens policy.
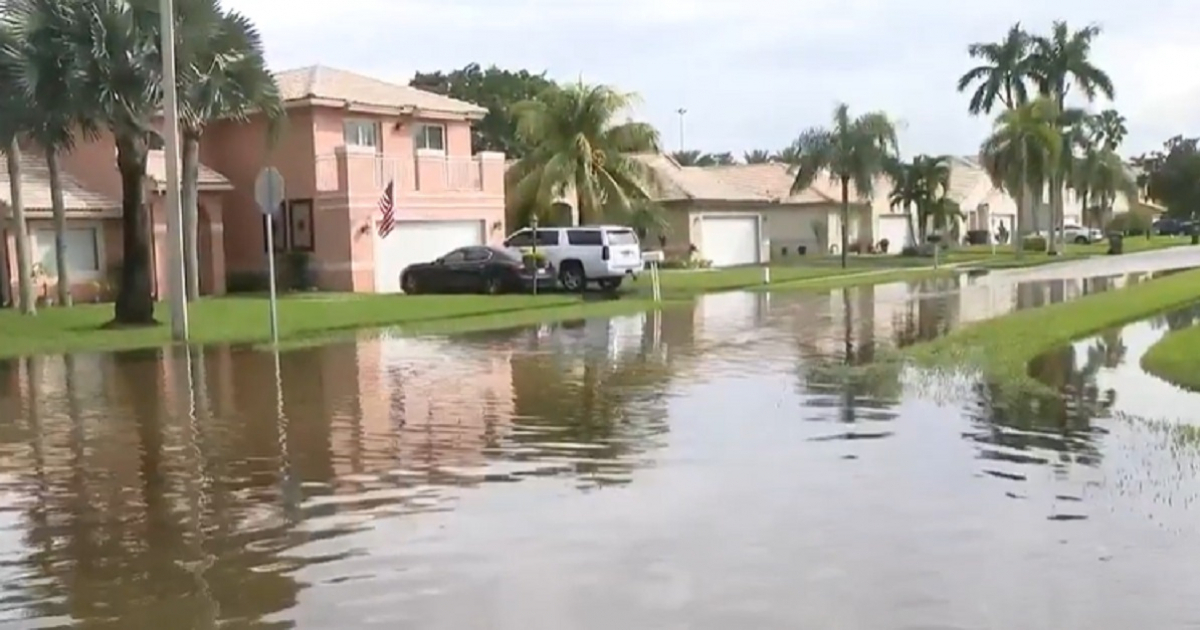
Michael Peltier, a spokesperson for Citizens, linked the new requirement to the flooding events that struck South Florida from November 17 to 20, where up to 16 inches of rain inundated properties far from traditional high-risk areas in Broward County.
"What we've observed following hurricanes and this week's massive rainfall on the other side of the state, particularly in Brevard County and the Space Coast, is that many customers outside flood zones are seeing their properties flooded," he stated.
Statistics support this warning: between 2014 and 2024, nearly one-third of NFIP claims originated from properties located outside high-risk zones.
Before renewing, homeowners should compare the two available options. Emily Rogan, Senior Director of Programs at United Policyholders, emphasized that differences between NFIP and private insurance "can look very different" in both price and coverage and advised evaluating both before making a decision.
In moderate-risk areas, NFIP insurance may cost between $500 and $800 annually, while private insurance could range from $350 to $600. However, price isn't everything: private policies often offer higher limits, replacement cost coverage for personal property, and temporary housing expenses, which NFIP generally does not include.
For residents of the unincorporated area of Miami-Dade, NFIP policyholders can receive up to a 35% discount thanks to the county's Class 3 rating in FEMA's CRS program. This benefit does not automatically apply to incorporated municipalities such as Hialeah or the city of Miami.
Citizens has already started sending notifications to policyholders ahead of renewal dates. Those without flood insurance at the time of renewal must rectify their status with their agent or risk losing eligibility with the state insurer.
New NFIP policies have a standard 30-day waiting period before they take effect, so it's wise to act early and not wait until the last moment.
To review official requirements and compare options, Citizens maintains a dedicated flood insurance page with updated information on current regulations.
Important Considerations for Florida Homeowners
Why is flood insurance becoming mandatory for Citizens policyholders?
The mandatory flood insurance requirement is a response to recent flooding events in Florida, where even homes outside designated high-risk zones have been affected. This aims to provide broader protection for homeowners.
How can homeowners obtain flood insurance?
Homeowners can obtain flood insurance through the federal National Flood Insurance Program (NFIP) or from private insurance companies. It's important to compare both in terms of coverage and cost.
What are the potential costs of flood insurance in moderate-risk areas?
In moderate-risk areas, NFIP flood insurance can range from $500 to $800 annually, while private insurance may cost between $350 and $600. However, private policies often offer more comprehensive coverage options.